Marnello produces the quantitative evidence that investment advisers and family offices need to document decisions: factor exposure decomposition, manager attribution, and statistical substantiation, each delivered with its methodology and a published validation record.
Founding-customer conversations open now, ahead of commercial launch
"Are your portfolio's tilts intentional?"
Momentum, low volatility, size, and reversal loadings on the submitted holdings, with the construction methodology attached.
Professional"Is this manager earning their fee?"
Return decomposition separating factor beta from residual alpha, with the estimation window, standard-error treatment and a 95% confidence interval on annualized alpha stated on the page. A measurement, not a verdict.
Professional"Can you substantiate that claim?"
The statistical record connecting a stated capability or performance claim to measured outcomes: methodology, data, computation, results and stated limitations.
Standalone · Enterprise"Why did you rebalance then?"
Volatility regime, cross-sectional dispersion, and correlation structure at the decision date, with historical analogues.
Core"Has diversification changed?"
Sector and asset-class correlation matrices and how they moved over the period.
CoreThe buyer has already decided. Marnello measures and documents the basis. No ratings, no targets, no opinion on advisability.
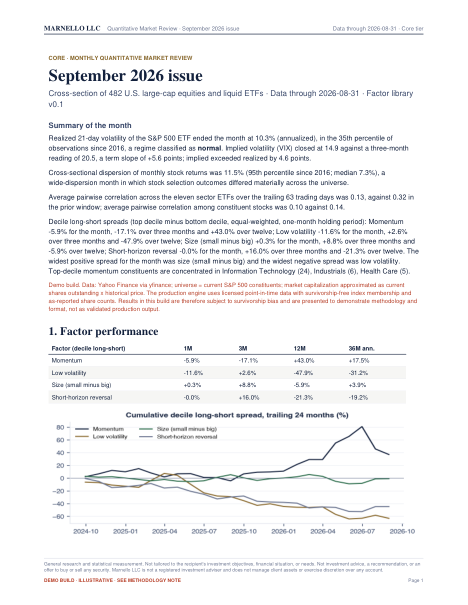
Product boundaries →October 2026 · 9 pages · data through 2026-09-30 · Firm email to open
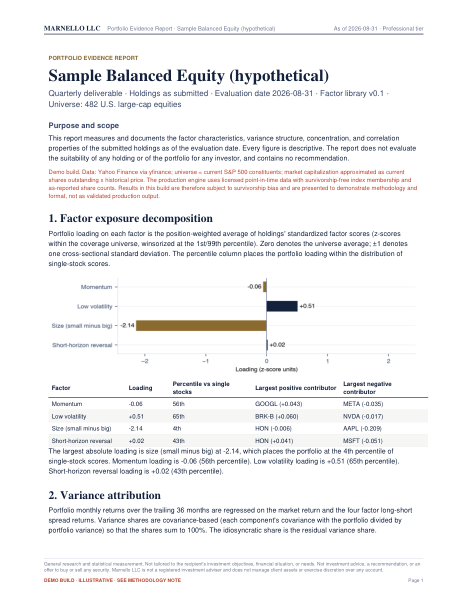
Sample Balanced Equity (hypothetical) · 4 pages · data through 2026-09-30 · Firm email to open
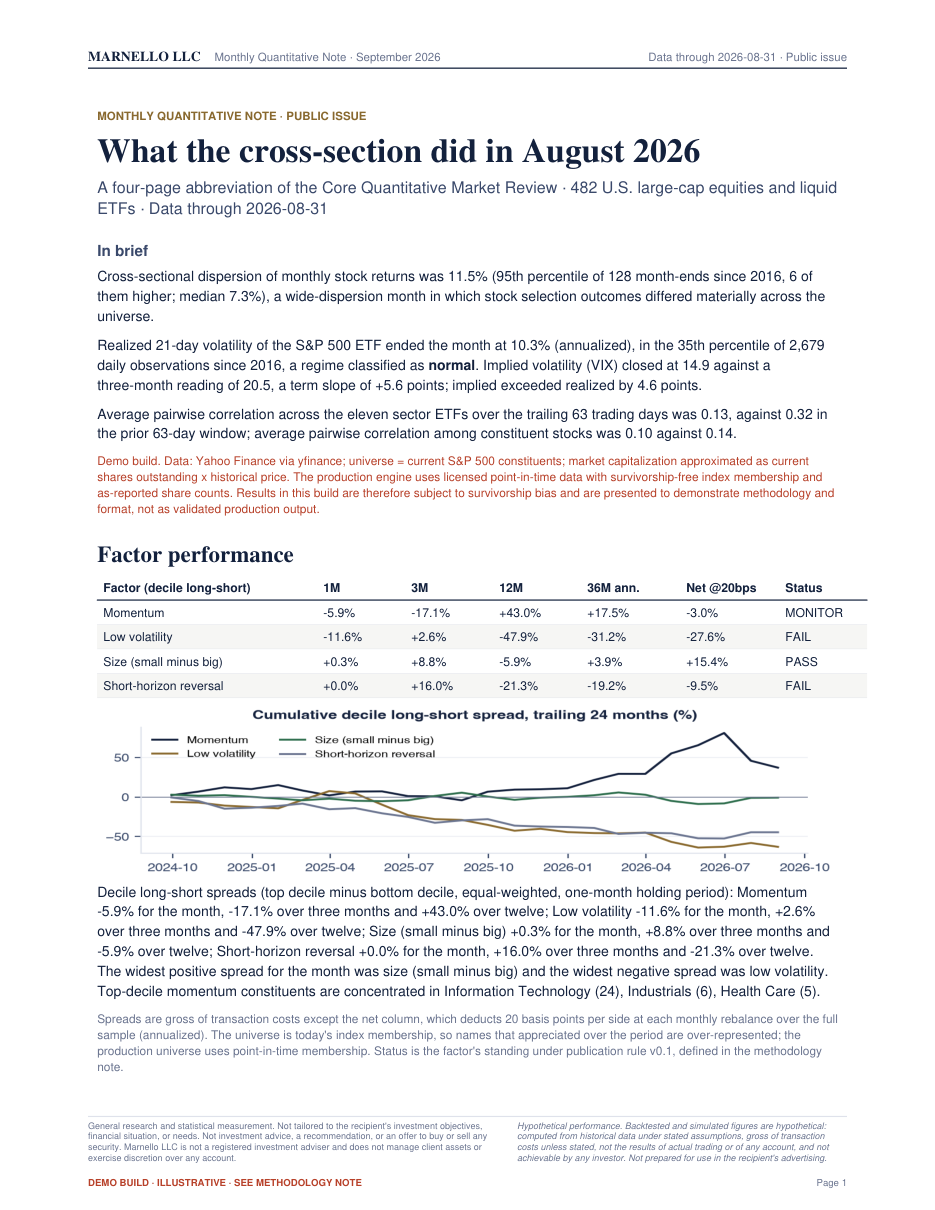
October 2026 · 4 pages · data through 2026-09-30 · Firm email to open
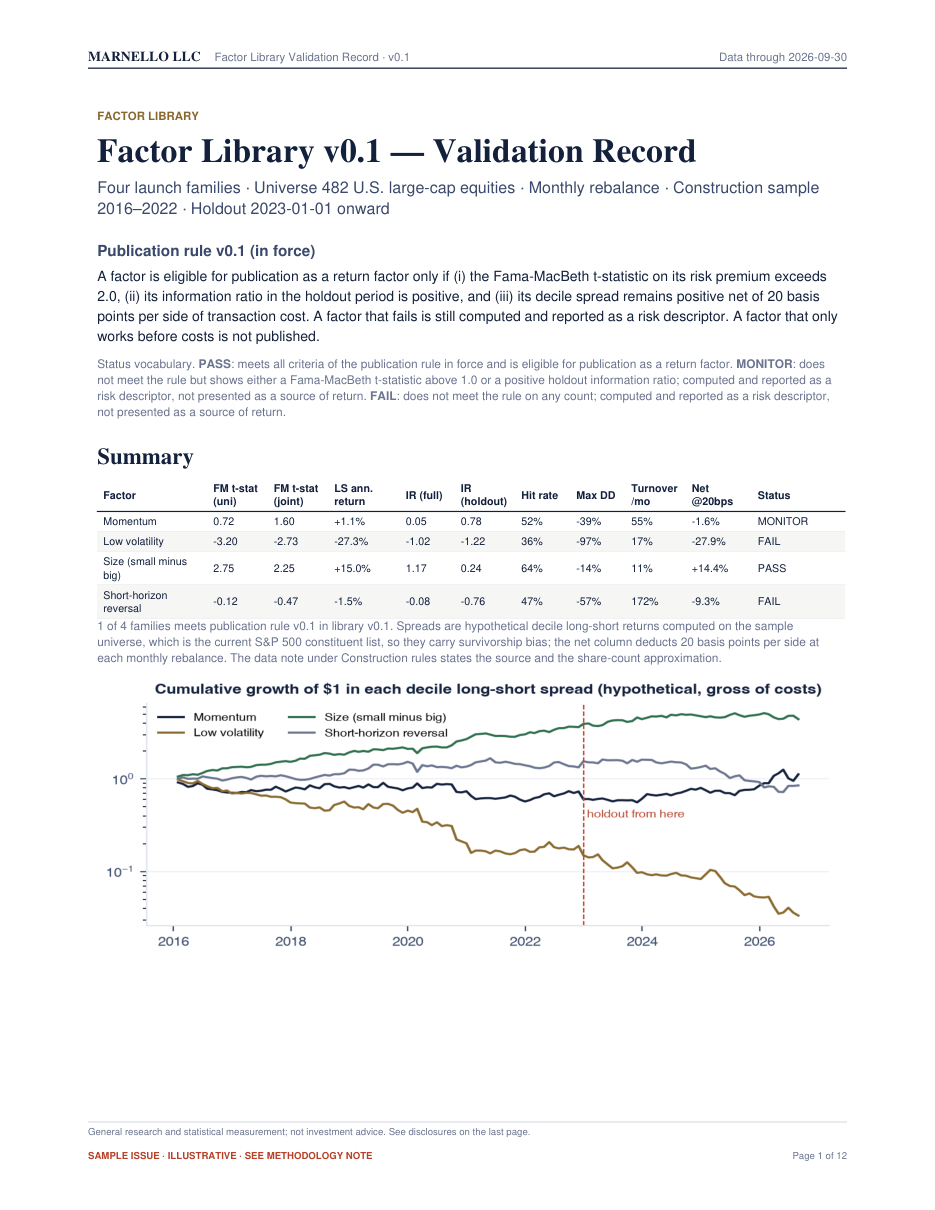
v0.1 · 12 pages · data through 2026-09-30 · Firm email to open
Sample issues run on publicly available daily prices, with the universe and share-count limitations stated in each document. All samples →
Look-ahead bias is testing against data that did not exist on the decision date. Why a backtest on today's index is not evidence.
Point-in-time data is as-reported values with their original publication timestamps, index membership as it stood on each date, and every computation constrained to what was knowable on the decision date. What the sample issues use instead is set out row by row. Validation record →
An examination request, a marketing claim under compliance review, or a client asking why performance lagged: each needs a dated measurement with the method attached.
Core · ProfessionalManager selection and oversight. Whether an active fee is buying alpha or factor beta, answered in a form that is defensible to a principal.
Professional · EnterpriseQuantitative infrastructure for firms selling to institutions, without building it: custom model licensing and, after launch, API access.
Enterprise · CustomFactor performance, dispersion, volatility regime, and correlation structure each month. Next issue: 2 November 2026.
Enter your firm email to open the sample issues. The Monthly Quantitative Note follows each month; unsubscribe any time.
Firm addresses only. The address is used to send the Note and to reply to enquiries, and for nothing else. Privacy.
Enter your firm email to open the sample issues. The Monthly Quantitative Note follows each month; unsubscribe any time.
Firm addresses only. The address is used to send the Note and to reply to enquiries, and for nothing else. Privacy.